CREDIT & SCORING
SME Loan Turnaround Time: What the 15-Day Clock Does Not Count
SME loan turnaround time under State Bank of Pakistan regulation R-16 is 15 working days, but the clock only starts once an application has complete KYC and financial data, so the intake and return-loop intervals before that point sit outside it and usually go unrecorded. Trazmo builds the intake, scoring and pipeline layer for regulated lenders in Pakistan and the GCC, and holds no credit risk itself.
The State Bank of Pakistan puts a number on SME loan turnaround time. Regulation R-16 of the Prudential Regulations for SME Financing, as updated on 16 July 2026, requires banks and DFIs to process SME credit applications within 15 working days. Internal Audit and the SME Governance Committee review compliance. Repeated breaches trigger action against the officers responsible.
Read the clause again and the interesting part is not the number. It is the condition attached to it. The 15 working days applies to "SME credit applications with complete KYC and relevant financial data."
Complete. That single word is the start condition of the entire regulated clock, and almost no lender records the moment it is met.
The clock has a start condition, not a start date
Most credit MIS systems record two dates well: application received and decision issued. Those are the dates that go into the TAT report, and by that measure a great many books look compliant.
What sits between them is a file that was received incomplete, returned to the borrower, resubmitted with the wrong statement period, returned again, and finally declared complete by an officer who did not timestamp the declaration because no field exists for it. Each of those loops is calendar time the borrower experienced and the report did not.
The regulator did not overlook this. R-19 requires a Credit Proposal Tracking Mechanism that registers every application centrally, issues a unique serial number for physical and online applications alike, and pushes status updates to the applicant automatically. R-6 requires the bank to hand the borrower the list of required documents at the point of applying. Both regulations exist because the gap before completeness is real, is known, and is where SME applications quietly age.
The instrumentation gap is narrower than it sounds. It is one event. The moment a file crossed from incomplete to complete.
Five stages, and where SME loan turnaround time actually sits
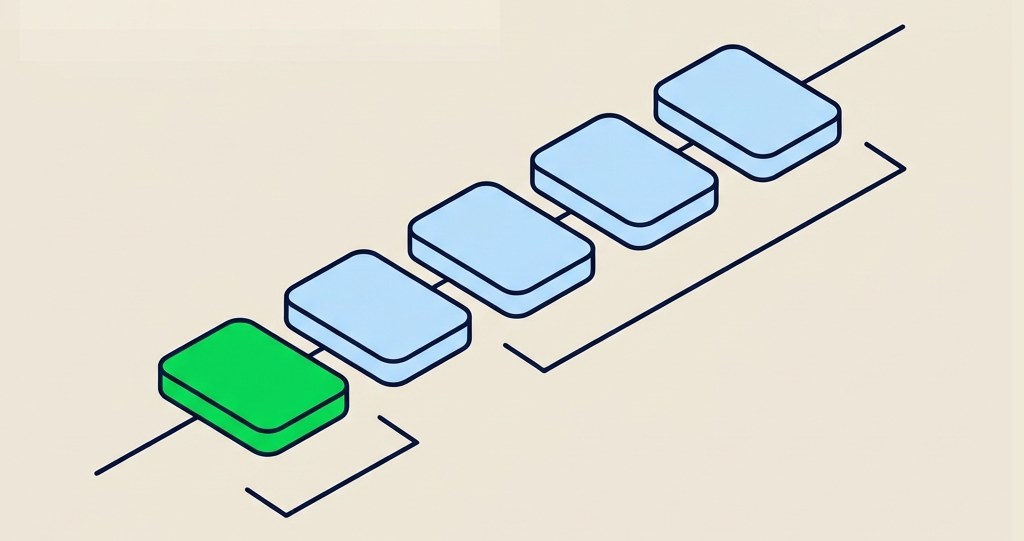
Here is the map. Run it against your own MIS and mark each row present or absent. The stages the clock does not count are the ones where nobody is accountable for elapsed time, which is exactly why they are where SME loan turnaround time goes.
| # | Stage | Inside the R-16 clock | Date pair to record | What the elapsed time actually measures | Who holds the file |
|---|---|---|---|---|---|
| 0 | Borrower assembles documents | No | Document list issued to borrower, first submission received | How legible your requirements are, and how much of the market self-selects out before applying | Borrower |
| 1 | Intake to completeness | No | First submission received, file declared complete | Return loops. The single most under-recorded interval in SME credit | Relationship or branch officer |
| 2 | Completeness to analyst pickup | Yes | File declared complete, analyst assigned | Queue depth, not analyst speed. Pure waiting | Credit operations queue |
| 3 | Analyst pickup to credit memo | Yes | Analyst assigned, memo submitted | Data assembly plus judgement, usually in that ratio | Credit analyst |
| 4 | Credit memo to decision | Yes | Memo submitted, approval or decline recorded | Committee calendars and quorum, not credit quality | Approving authority |
Row 1 is the one to build first. Rows 2 through 4 already exist in most core systems in some form. Row 1 usually does not exist anywhere, which means the regulated clock in your TAT report is starting at a date nobody chose deliberately.
Row 0 is harder and worth doing second. It is not a system field, it is a log of when the document list went out. Pakistan is a single lender market in practice: the bank is the lender, and the borrower carries its own file from one institution to the next doing its own routing. Every day of row 0 is a day in which a competitor's relationship officer can take the same borrower with a shorter list.
What the stages are actually measuring
The value of splitting the clock this way is that each interval has one dominant cause, and the causes need different fixes.
Stage 1 is a document quality problem. In MENAP, statements arrive as scanned passbooks, PDF exports from a dozen core banking templates, and partially digitised files from banks mid migration. A completeness check calibrated on one bank's format produces inconsistent accept and reject decisions on statements from the rest. DocuMind runs extraction and validation at intake rather than after the file has entered the queue, so incompleteness surfaces in minutes instead of after the first analyst opens the file. Every return loop avoided is at least one business day removed from an interval the regulator does not even count.
Stage 2 is not a speed problem at all. It is queue depth, and it responds to routing, not to hiring. A file waiting six days for an analyst tells you nothing about that analyst.
Stage 3 is the only stage where credit judgement is genuinely happening, and in manual operations most of it is spent assembling rather than deciding. Sentinel scores the file from normalised transaction data before an analyst opens it, so what lands on the desk is a scored file with flagged exceptions rather than three separate exports to reconcile.
Stage 4 is a calendar problem wearing a credit decision's clothes. It is fixed by delegated authority thresholds, not by better memos.
Flux, the lender dashboard, holds each file by stage with a clock running on it, so the queue sorts by age rather than by who called this morning. The five rows above are what that clock should be counting, including the two the regulator does not.
Do this before the next TAT review
Pull your last 30 SME files. For each one, find the date the file was declared complete. If that date does not exist as a field, you have found the answer already, and the fix is a single timestamp on the completeness event rather than a systems programme.
Then measure stage 1 across those 30 files. Compare it against the 15 working days the regulator gives you for stages 2 through 4 combined. If stage 1 is longer than the regulated clock, and on manual books it often is, then SME loan turnaround time at your institution is not a compliance question. It is an intake question that compliance never had visibility into.
R-16 gives you 15 working days for the part of the process the borrower cares about least. The part they measure starts the day they first asked what you needed.
Trazmo builds the intake, scoring and pipeline layer this runs on. More on how the five stages look instrumented end to end.